See the capacity operators are offering now, and the sites coming available in the next 12 months.
Operators tell the agents they work with before they tell the market. We list what they have shared, by market and date, and name the building on a call. One request gets you quotes you can compare, at no cost to you. See what is available now →
No cost to your teamNo obligation to buy anything
We never sell your informationWork directly with a colocation scout
Every option datedEnergized or queued, with the confirmation date
Named on a callListed by region and date, the building named on a call
A sample of the operators active in these markets, not a partner list. Logos are the trademarks of their respective owners and imply no endorsement of Colocation Scout.
Why use a scout
One request. Every provider. Side by side.
Watch: why use a scout (48 seconds)We contact every provider in your market, line the quotes up side by side, and stay with you to signature. The same price as going direct, or better, and it costs you nothing.
Two things follow. Scale buys less discount than it used to, because large contiguous blocks are the scarce product. And the renewal clause now matters more than the opening rate. Negotiate the escalator and the renewal before the headline number.
Source: CBRE, Equinix and Digital Realty, latest available Q2 2026. Full sourcing for every figure is on the pricing benchmarks page.
Explore top markets
The four largest U.S. markets.
No. 1 U.S. market
Northern Virginia
Ashburn and Data Center Alley
4,182 MWinventory
0.3%vacancy
10.8 MWavailable
The deepest ecosystem and the tightest vacancy in the world. On the published numbers the market is closed, yet deals still close every week against requirements the market never sees.
The fastest-growing top-four market, with central geography and a huge construction pipeline. Power interconnection and preleasing still shape real delivery options.
A central connectivity and enterprise hub with strong financial-services demand. Western submarkets are expanding, while utility delivery dates remain the central constraint.
We take requirements into 90 U.S. markets and submarkets. Forty-eight have a published market guide today, with the evidence available for each market stated plainly. The rest are covered by the same sourcing process, and their guides are being written.
Inventory figures are CBRE Q1 2026. Filing and facility counts are our own collection from public construction records, current to 26 October 2026. A construction filing proves something is being built. It never proves space is available to lease.
Tier 1, primary markets and submarkets22 markets
The deepest inventory and interconnection, and the tightest availability. Broken out by submarket because a Dallas core requirement and an Alliance requirement are different searches.
Names in blue have a published market guide. The rest do not have a guide yet, which changes what we can show you here, not whether we can source in them.
Everything here is open. One thing is not on the internet.
Pricing, market fundamentals and lease structure are all knowable, and we publish them. Which operator can serve 500 kW at your density on your date is not published anywhere, at any price.
Colocation pricing
Explore current rates and what drives them, from install charges to escalators and renewals.
Colocation Scout is powered by Bridgepointe Technologies, a technology advisory firm since 2002. You get one advisor, the market data on this site, and the provider relationships behind it. You pay nothing. Providers fund the advisory, and we say so.
Bridgepointe clients include
NVIDIA
Microsoft
Oracle
Cisco
Salesforce
CrowdStrike
Charles Schwab
PayPal
Mastercard
Netflix
Adobe
Marriott
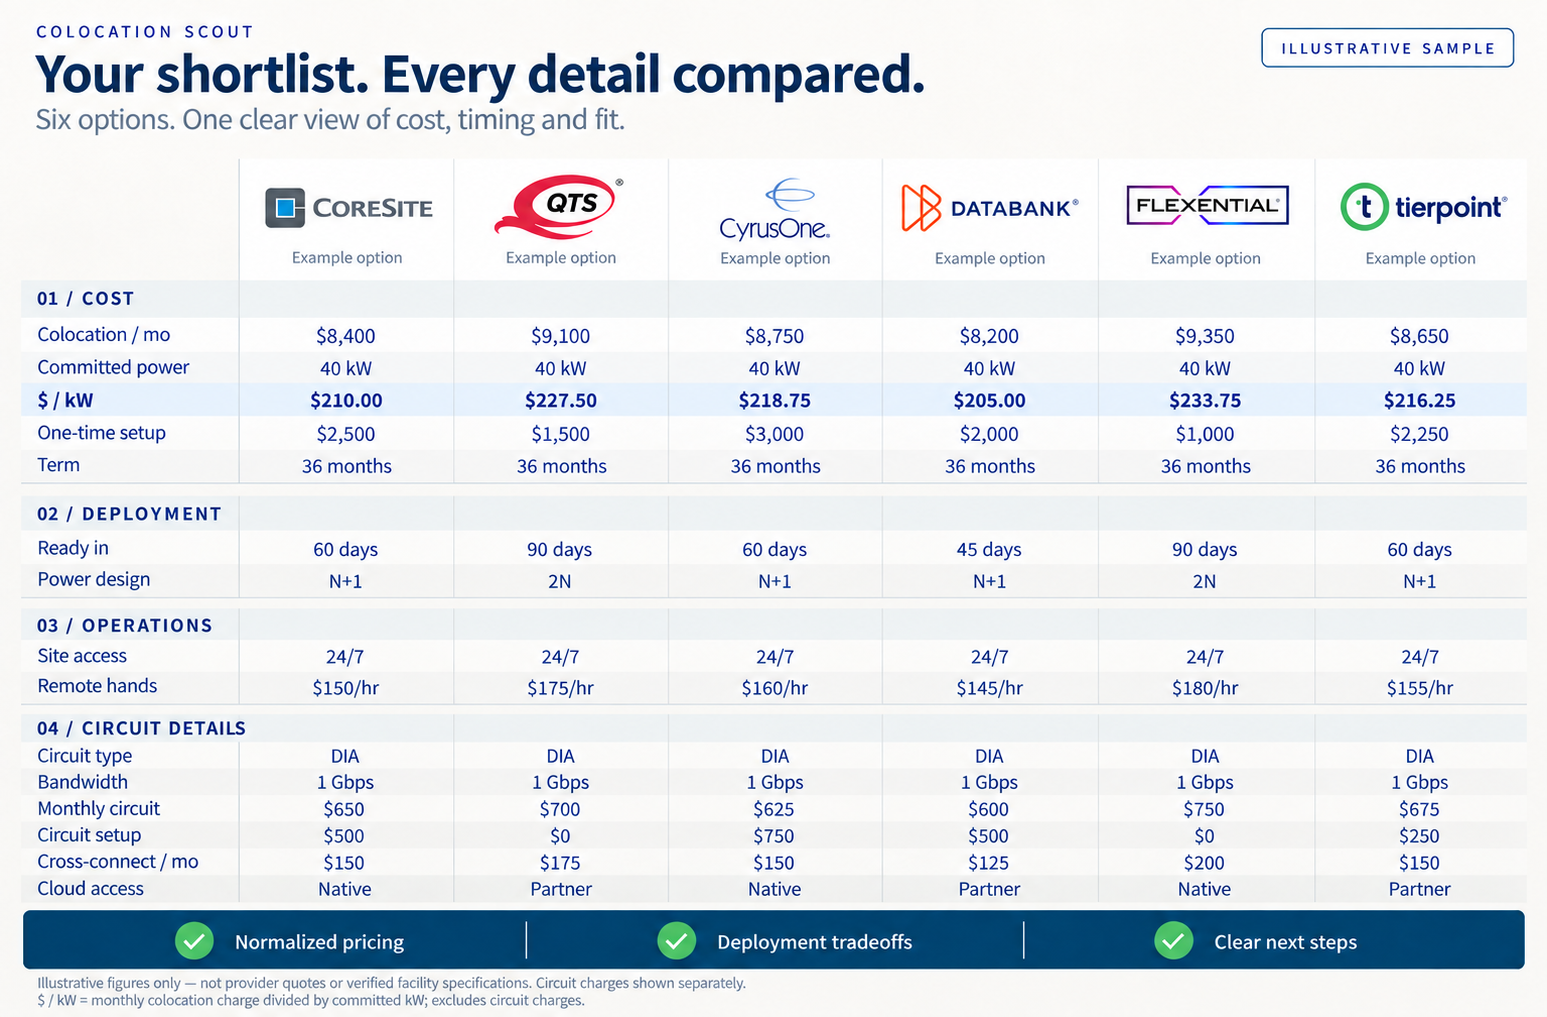
What you get back: every quote on one sheet, priced per kW so the options compare. This is a sample.
75+ Fortune 500 clients
Including more than 20 of the Fortune 100, with 97% client satisfaction.
1,200+ data center and cloud projects
Requirements assessed, capacity sourced and providers selected.
Move-in concessions
We regularly negotiate concessions, such as free months or reduced early billing, to cover the overlap while you migrate.
One requirement, every fit
Bridgepointe partners with 380+ technology providers. We take one normalized requirement to that market and bring back a side-by-side comparison you can actually decide from.
No public service lists colocation capacity, so we keep our own. Our list shows what operators have told us they can deliver, by market and date. The building is named on a call.
We report usable kW/MW in a named hall, energized or queued, with the date the operator confirmed it. Availability that is not dated is not availability.
The buyer pays nothing. Providers fund the advisory, and we disclose the relationship. We help you find and compare colocation options, and we never sell your information.
FirstEnergy said in an October 27, 2026 investor presentation that contracted data center demand across its five state footprint has nearly doubled since year end 2025, to about 7.9 GW of cumulative demand forecast for 2036. It counts another 19 GW of pipeline demand, says it is in active contract negotiations with about 4 GW, and lists 117 GW of large load studies outside its pipeline. Contracted means a contract to construct facilities and/or an electric service agreement. In West Virginia, it says it is negotiating with a data center customer to take the long-term output of a planned gas plant. [Source 1]
FirstEnergy service territory in Ohio, Pennsylvania, Maryland, West Virginia and New Jersey · Utility demand forecast. FirstEnergy reports about 7.9 GW of contracted cumulative data center demand forecast for 2036 (construction contracts and/or electric service agreements), 19 GW of pipeline demand and 117 GW of load studies outside the pipeline. West Virginia gas plant off-take with a data center customer under negotiation. No project level status established. As of October 27, 2026.
Galaxy Digital said on October 27, 2026 that Phase II of Helios I, its CoreWeave leased data center at the Helios campus in Dickens County, Texas, is fully financed and under construction, with data hall deliveries scheduled to begin in the second quarter of 2027. All 133 MW of Phase I critical IT load was delivered to CoreWeave by the end of the second quarter. Galaxy says it is in discussions with prospective tenants for 830 MW of approved capacity at Helios II that is not yet under lease, and that its Texas power pipeline now totals over 5.7 GW of potential capacity. [Source 1] [Source 2]
Helios campus, Dickens County, Texas, about 60 miles from Lubbock · Helios I Phase I Leased, 133 MW critical IT delivered to CoreWeave by end of Q2 2026 (company statement). Phase II Under construction (company statement), 260 MW contracted critical IT, data hall deliveries scheduled to begin Q2 2027. Phase III Leased, 133 MW critical IT, rent from 2028. Helios II: 830 MW of approved power capacity not yet leased. No capacity Available to new customers established. As of October 27, 2026.
Putnam County, Georgia filed a Development of Regional Impact review with the state on October 26, 2026 for Eatonton 379, a proposed data center development on about 543 acres with about 11 buildings totaling about 3.5 million square feet. The filing lists an estimated peak connected electrical load of about 520 MW, names Tri-County EMC or Georgia Power as the energy supplier, and gives an estimated value at build-out of about $3.5 billion with completion in 2031. The developer is seeking a rezoning and a conditional use. Putnam County has a moratorium on data center land development permits that it extended on October 21, 2026 to November 17, 2026. [Source 1] [Source 2] [Source 4]
Unincorporated Putnam County, Georgia, off Glenwood Spring Road (33.304423, -83.406540) · Proposed. Developer seeking a rezoning and a conditional use from Putnam County; Georgia DRI #4861 filed October 26, 2026 with estimated completion in 2031. Putnam County data center moratorium extended October 21, 2026 to November 17, 2026. No zoning approval, utility agreement, construction, energization or availability established. As of October 27, 2026.