How much does colocation cost in Austin and San Antonio?
Recent quotes we received for Central Time Region / Midwest ran $245 to $295 per kW per month for up to 500 kW, falling to $160 to $190 above 1 MW.
| Deployment | Monthly rate | Source |
|---|---|---|
| Up to 500 kW | $245 to $295/kW-mo | Our quotes |
| Over 500 kW to 1 MW | $200 to $240/kW-mo | Our quotes |
| Over 1 MW | $160 to $190/kW-mo | Our quotes |
We have no current published asking-rent band for Austin or San Antonio to cite, so the Central Region quotes are the figure to plan with.
Smaller deployments cost more per kW. These are recent quotes we received, not a statement that space is available. Cross-connects, remote hands and one-time setup are extra. Operators often give 2–3 free months on a new term. See every region's quote ranges.
Austin cabinet and cage prices
Smaller deployments are priced per cabinet or per cage rather than per kW. Use these monthly ranges to set a first-pass budget. They are not provider offers, and a building on this page is not a claim that space is available in it.
| Requirement | Monthly range | Power and bandwidth assumed |
|---|---|---|
| 1 to 2U | $360 to $485/mo | 1 to 3 A at 120 V, 1 to 5 TB of transfer |
| Half cabinet, 24U | $1,195 to $1,360/mo | 2 to 3 kW, 100 Mbps to 1 Gbps |
| Full cabinet, 48U | $1,405 to $1,665/mo | 2 to 5 kW, 100 Mbps to 1 Gbps |
| High-density cabinet, 48U | $2,105 to $5,130/mo | 10 to 17 kW, three-phase |
| Private cage, 4 racks | $5,240 to $6,300/mo | 5 kW per rack, 1 Gbps |
| High-density private cage, 4 racks | $14,505 to $22,205/mo | 20 kW per rack, 1 Gbps |
Based on quotes we received in the 30 days before 21 October 2026. Taxes, cross-connects, remote hands and one-time costs are extra. Replace these ranges with a normalized written quote before approval. How power is billed is covered in how colocation power is billed.
Get Austin and San Antonio colocation prices for your setup
Tell us the racks, power and timing you need. A scout comes back with matching Austin and San Antonio options and quoted prices.
Capacity operators are offering here
- 200 kW in Austin, available now (confirmed October 30, 2026) AC-040
- 110 kW in Austin, available now (confirmed October 22, 2026) AC-004
- 150 kW in Austin, available Q1 2027 (confirmed October 22, 2026) AC-014
Operator-reported and dated, not a reservation. The building is named on a call. See every listing.
What providers in Austin and San Antonio post as a list price
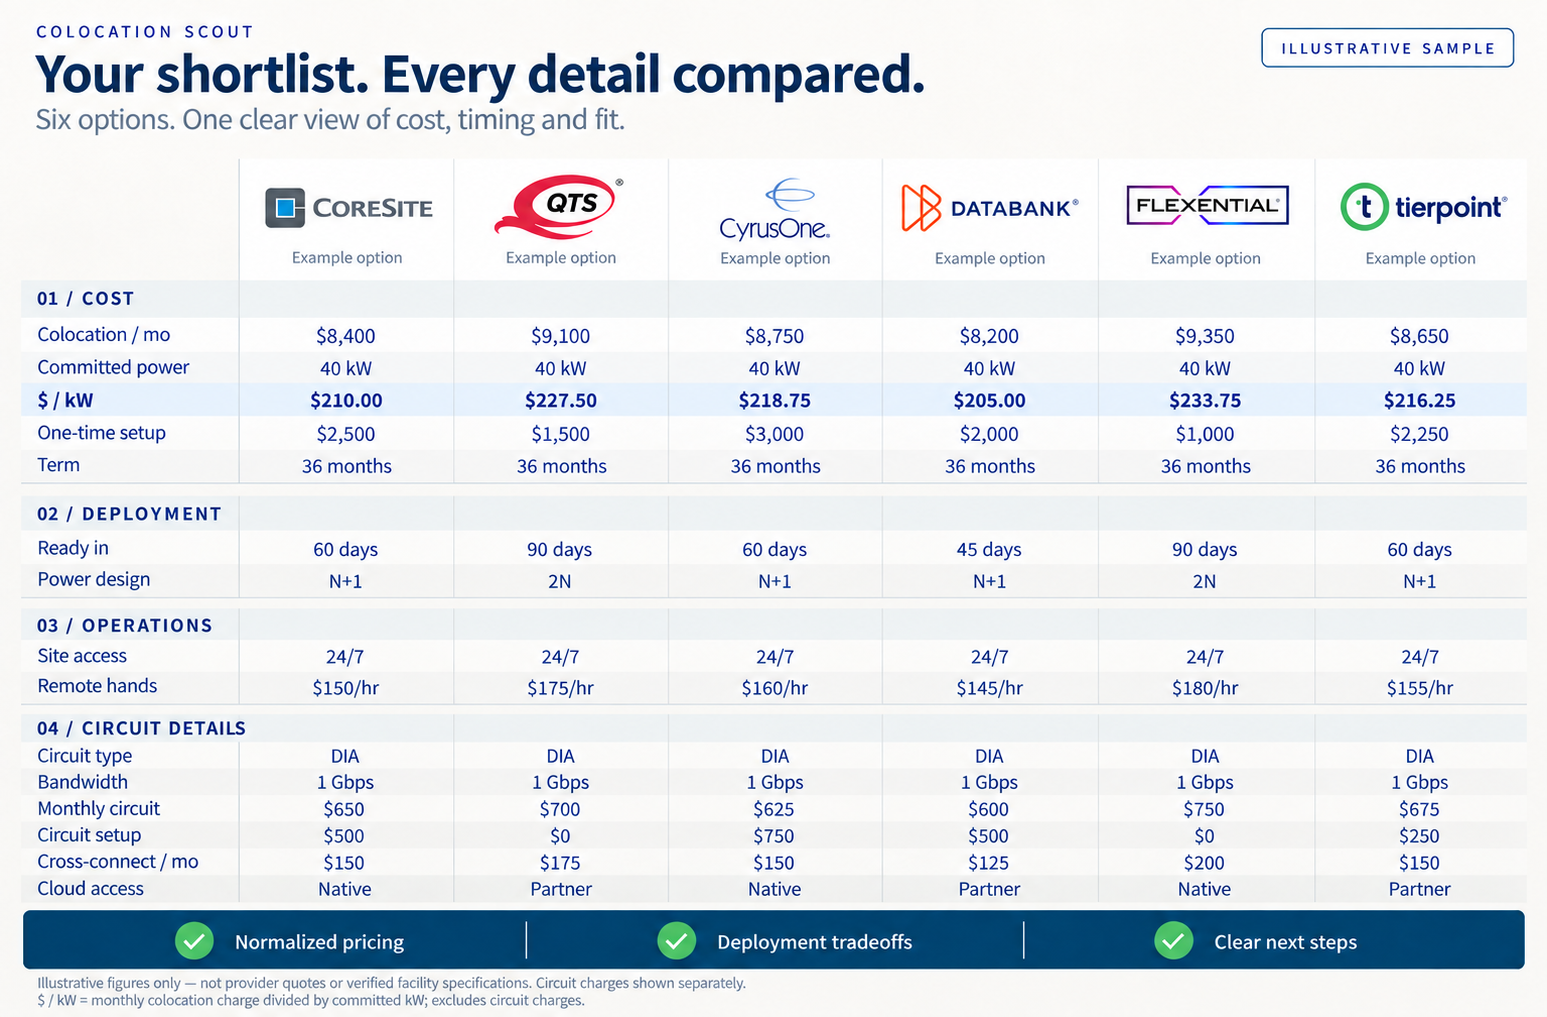
Most colocation in Austin and San Antonio is quoted, not posted. The providers below are the exception: each publishes a monthly price on its own website, and every row links to that page. They are smaller regional operators. The large operators here do not publish prices at all, so read these as a floor and a sanity check, not as what an enterprise contract lands at.
| Monthly | Provider | Offer | Power included | Per usable kW | Bandwidth |
|---|---|---|---|---|---|
| From $997 | Thin-nology | Full rack, 42U. Pflugerville, near Austin | 20A at 120V (1.92 kW usable) | $519 | Quoted separately |
| From $1,310 | Bexar Datacenter | Full cabinet, 42U. San Antonio. Month to month | Included, rating not stated | Power not stated | 100 Mbps unmetered |
Each price was read on the provider's own page on the date shown. Usable kW is 80% of the circuit rating, with a redundant A+B pair counted once, and is only worked out where the provider states both amps and volts. "From" is the provider's own word for a starting price. Providers whose networks carry spam or abuse flags are left out whatever their price. A posted price is not availability, and bundles differ in bandwidth and power, so compare the whole row rather than the first column. How power is billed is covered in how colocation power is billed.
Send it over and a scout will tell you how it compares with these posted prices and with the published benchmarks for this market. There is no obligation.
Who is actually plugged in across Austin and San Antonio
A building existing and a building being connected are different facts, and only one of them decides whether your traffic can get where it needs to go cheaply. These figures come from PeeringDB, which the network operators themselves maintain, so every row below links to the building's own public entry.
| Measure | Figure | What it means |
|---|---|---|
| Buildings listed | 19 | Registered in PeeringDB across Austin and San Antonio, by 14 operators |
| Buildings with a network present | 16 | 3 carry no network presence, which usually means single tenant or simply unregistered |
| Network presences | 72 | Counted per building, so a carrier in three buildings counts three times |
| Internet exchange presences | 6 | Where you can reach many networks through one port instead of many cross-connects |
| Carrier presences | 16 | The physical transport choice you can buy without leaving the building |
| In the densest building | 28% | H5 Data Centers San Antonio holds 20 of the market's network presences |
The most connected buildings here
| Networks | Building | Operator | Exchanges | Carriers |
|---|---|---|---|---|
| 20 | H5 Data Centers San Antonio | H5 Data Centers | 1 | 2 |
| 15 | Data Foundry Texas 1 | Data Foundry, Inc. | 1 | 1 |
| 5 | CyrusOne Austin (Met 2) | CyrusOne Inc. | 1 | 2 |
| 4 | CyrusOne San Antonio | CyrusOne Inc. | 0 | 2 |
| 4 | DataBank Austin (AUS1) | DataBank, Ltd. | 0 | 0 |
| 4 | Element Critical Austin AUS1 | Element Critical, LLC | 1 | 1 |
| 4 | LightEdge Austin 2 (AUS2) | LightEdge Solutions | 0 | 0 |
| 3 | Data Foundry Austin 1 | Data Foundry, Inc. | 1 | 0 |
From PeeringDB, which is maintained by the network operators present in these buildings rather than by the landlords, which is what makes it worth more than a directory. Two limits. Entries are voluntary, so a building showing no networks may be single tenant or may simply never have registered. And a network being present says nothing about whether the building has space, power or a price for you: that is still a call.
Market profileThe rule that changed on 3 August 2026
Governor Abbott halted approvals for any data center seeking a new ERCOT grid connection, pending a joint audit by the Public Utility Commission of Texas and ERCOT. ERCOT paused its "batch zero" interconnection review the same week. Developers must now disclose tax incentives, power use and generation, water use and cooling method, local impact measures, and ownership. Projects that fail "must be denied connection to the Texas grid".
ERCOT's queue holds more than 1,800 projects and over 474 GW, roughly 90% of it data centers. That is more than five times the grid's record peak demand.
The freeze does not touch facilities already operating or already under construction and connected. It does not touch sites with their own on-site generation, or El Paso, which is outside ERCOT. No end date has been given.
If your date falls within eighteen months, you are buying from buildings that already have power. That set has stopped growing. The option of waiting for the next campus is gone.
Reported by the Texas Tribune on 3 August 2026 and KERA News on 4 August 2026.
Why Central Texas is growing this fast
Land, an independent grid with its own interconnection process, a large technical workforce and corporate relocation drive enterprise demand alongside hyperscale and AI. Most growth is north and south of the Austin metro, where land is available at scale.
CBRE reports under-construction capacity more than quadrupled year over year to 463.5 MW. That is the most of any secondary market and the fourth most of any market. Delivered at once, it would rank Central Texas second behind Northern Virginia.
189.7 MW
Standing inventory today.
463.5 MW
Under construction, more than quadruple the prior year.
96% preleased
Of that pipeline, before it opens.
1.8% vacancy
A record low.
Source: CBRE on Central Texas and CBRE North America Data Center Trends H2 2025. Figures describe the combined Austin and San Antonio market, not a specific facility.
At 96% preleased, roughly 19 MW of the 463.5 MW under construction is uncommitted. Announced capacity is not available capacity.
Austin and San Antonio are two markets, not one
The downtowns are about eighty miles apart. They sit under different city-owned utilities, Austin Energy and CPS Energy, and draw water from different sources. San Antonio holds the interconnection. Austin's outskirts hold the construction. For users or systems in Austin, a San Antonio building adds a round trip on every request. That suits backup and archival, not latency-sensitive work. Decide which city you must sit near first.
Where the market actually is, submarket by submarket
San Antonio
30 facilities, the most here, and nearly all the network depth. H5 Data Centers San Antonio alone carries 21 of the market's 74 network presences. Best for carrier choice and existing space.
Austin proper
18 facilities and the second interconnection cluster, around Data Foundry Texas 1 and CyrusOne Met 2. Land and power are tight, so deals are enterprise-sized, not megawatt-scale.
Taylor and Hutto
21 facilities, almost all planned or under construction. Oncor built eastern Williamson County transmission for Samsung's fab and hyperscale developers followed. Most exposed to the connection freeze.
Cedar Creek and Bastrop County
9 facilities and the largest buildings, including two planned EdgeConneX buildings of 960,000 SF each. Not the Austin metro's serving utility. Confirm who delivers the power.
Round Rock
6 facilities, including a 300,000 SF Sabey building under construction. North of Austin's constraints, south of Taylor's delivery risk.
Facility counts come from our verified inventory and network counts from PeeringDB, both set out below. A verified building is not a statement that space inside it is available. See what verified covers.
What SB 6 does to a requirement of 75 MW or more
Texas Senate Bill 6, signed in June 2025, sets a separate ERCOT regime for loads of 75 MW or more. Four things apply.
- An initial transmission screening study costs at least $100,000, paid up front.
- Loads interconnected after 31 December 2025 must let ERCOT curtail them directly in a firm load shed. Data centers are not exempt.
- You must disclose any substantially similar request elsewhere in Texas.
- Netting on-site generation against the load needs a 120 day ERCOT study and a 60 day PUCT approval.
The implementing rule, 16 TAC 25.194, is still a draft, published 12 March 2026. As proposed it adds a non-refundable interconnection fee of $50,000 per MW, financial security at the same rate, study fees of $100,000 up to 250 MW and $300,000 above it, and full customer payment of interconnection costs.
Colocation tenants rarely sign under SB 6, because the operator interconnects. The cost still reaches your power rate. Ask whether your building can be curtailed, what that does to your SLA, and who carries the cost.
ERCOT's isolation also makes extreme weather a design question. Ask how the facility performed in past events, what on-site generation and fuel it holds, and how long it rides through a regional event without resupply. On-site generation also exempts a project from the connection freeze.
Statute summarised from Bracewell. Draft rule status from Greenberg Traurig, March 2026.
Water splits this market in half
San Antonio draws on the Edwards Aquifer. After more than two years at Stage 3, the San Antonio Water System eased to Stage 2 on 4 August 2026, with the aquifer at 650.3 feet. Austin draws on the Highland Lakes through the LCRA and has been in its baseline Conservation Stage since September 2025.
Water use is one of the disclosures in the state audit. Two San Antonio data centers used a reported 463 million gallons across 2023 and 2024 during drought, per San Antonio Water System records.
Ask for the cooling method by name, not a PUE. Closed loop and air cooled buildings carry almost no water exposure and cost more to run. Evaporative buildings are cheaper and carry the regulatory risk.
Drought stages from the San Antonio Water System via Texas Public Radio and Austin Water. The consumption figure is second-hand reporting of SAWS records rather than a filing we hold, and is published here.
Pricing is moving, especially at scale
CBRE reports pricing above $200 per kW per month, levels last seen in 2011 and 2012. Deployments of 10 MW and above have risen by up to 19% since the second half of 2024, the reverse of the usual volume discount. Large contiguous blocks are scarce and AI occupiers compete for them.
- Price standing capacity separately from a future phase.
- Ask for the escalator over the full term. Fast-growing markets reprice hard at renewal.
- Confirm the ERCOT interconnection position for any capacity not yet energized.
- Price Dallas-Fort Worth for the same requirement. Same state, same grid operator, much deeper market.
When Central Texas is right, and when it is the wrong choice
- Right if you need central US coverage in a building that already has power.
- Right if Texas operations or workforce justify the location, or the requirement fits the uncommitted remainder.
- Wrong if you are buying the pipeline. Roughly 19 MW of the 463.5 MW under construction is uncommitted, and the freeze stops new supply on any known timetable.
- Wrong if you need network depth. 74 network presences across two cities, more than a quarter in one San Antonio building, is thin next to Dallas-Fort Worth.
- Run Dallas-Fort Worth in parallel from the first call. Same grid operator and SB 6 regime, roughly five times the standing inventory.
- Shortlist energized buildings only and get uncommitted megawatts named in writing. Treat any date that depends on a new ERCOT connection as unknown until the audit closes.
- Ask which utility serves the building, whether the load can be curtailed, and what the cooling method means for water. See the RFP checklist.
What has been announced in Austin and San Antonio
Announcements are not filings. Nobody has to build what they announce, the figure is the one the developer chose to publish, and the date moves. They are here because megawatts are what a requirement is measured in, and because the size of what is coming changes who will take your call. Every figure below links to a published report that states it, and was checked against at least one other independent report before it was written down.
| Capacity | Operator | Project | What was announced |
|---|---|---|---|
| 2 GW | Tract | Caldwell County park | 1,515 acres between Austin and San Antonio, 360 MW grid connection due 2028. Announced capacity at full build-out |
| 1.2 GW | CloudBurst | San Marcos campus | 706 acres in Guadalupe County, three 400 MW phases, first from 2026. Announced capacity at full build-out |
| 600 MW | Skybox Datacenters and Prologis | PowerCampus Austin, Hutto | Up to 4 million SF, 25 miles north of downtown Austin |
| 300 MW | Rowan Digital | Cinco campus, Medina County | 440 acres, fully operational expected 2027 |
Announced capacity is collected by hand from trade reporting and company statements, and each figure links to the report it came from. It is kept apart from the permit record below and never added to it: one is a document a jurisdiction issued, the other is a plan a company published. Neither is availability.
Every Austin and San Antonio facility we track
107 data centers across Austin and San Antonio, from our verified inventory. It is the layer that says whether a building exists yet, which no permit record answers directly.
| Status | Facilities | What it means for a search |
|---|---|---|
| Operational | 30 | Standing and running. The only layer that can hold a requirement this year |
| Under construction | 14 | Steel is up. Reachable for a date 6 to 18 months out, and usually pre-leasing now |
| Planned | 63 | Announced or entitled, not yet built. Treat every date on these as a forecast |
| Building area on file | 11,595,402 SF | Across the 46 facilities where a size is recorded, of 107 |
| Largest single building | 960,000 SF | EdgeConneX, Cedar Creek |
Operators with the most facilities here: CyrusOne (13), EdgeConneX (9), Skybox Datacenters (9), Iron Mountain Data Centers (7), Switch (7), KDC (6), Stream Data Centers (6), CloudHQ (5), Rowan Digital Infrastructure (4), Tract (4).
Where they cluster: San Antonio (30), Austin (18), Taylor (14), Cedar Creek (9), Hutto (7), Round Rock (6).
The largest buildings coming to this market
77 facilities here are under construction or planned. These are the ten largest by floor area, and a size on file is not a promise of a delivery date.
| Operator | Status | Building size | Where |
|---|---|---|---|
| EdgeConneX | Planned | 960,000 SF | Cedar Creek, TX |
| EdgeConneX | Planned | 960,000 SF | Cedar Creek, TX |
| Skybox Datacenters | Planned | 735,000 SF | Hutto, TX |
| Skybox Datacenters | Planned | 735,000 SF | Hutto, TX |
| Skybox Datacenters | Planned | 735,000 SF | Hutto, TX |
| Vantage Data Centers | Under Construction | 432,800 SF | San Antonio, TX |
| Vantage Data Centers | Under Construction | 360,000 SF | San Antonio, TX |
| Sabey Data Centers | Under Construction | 300,000 SF | Round Rock, TX |
| Stream Data Centers | Planned | 300,000 SF | San Antonio, TX |
| Stream Data Centers | Planned | 300,000 SF | San Antonio, TX |
From our verified inventory rather than from a public record, so these rows carry no filing link and street addresses are held back. These buildings are verified, which is not the same as their space being available: every facility above may be full, pre-leased, or closed to your size. Finding out is a call, not a lookup. See what a verified building does and does not mean.
What the public construction record shows in Austin and San Antonio
TCEQ air permits filed in the Bexar and Travis county corridors. Every figure below is a count of filings we collected ourselves, and every row links to the record it came from.
| Measure | Figure | What it means |
|---|---|---|
| Filings we track | 221 | Deduplicated. Across 3 sources, May 1985 to June 2026 |
| Filed in the last 12 months | 8 | The live rate of construction activity, which is the number that moves |
| Tenant fit-out filings | 73 | A customer is landing in a named building. The strongest signal in the set |
| Distinct addresses | 136 | Separate sites in the record, not separate buildings |
| Largest capacity in the record | 9 MW | Stated on 3 of 221 filings. Capacity is rarely published, so this is a floor, not a market total |
| Largest floor area filed | 775,644 SF | One permit, not a campus total. Floor area is published far more often than capacity |
| Operators we can name | 7 | 53 of 221 filings name a recognizable operator. The rest name an engineer, a builder or a holding company |
Operators appearing by name: QTS (15), Vantage Data Centers (14), Microsoft (9), CyrusOne (6), Switch (6), Amazon Web Services (2), STACK Infrastructure (1).
The filings that state a capacity
Most permits never mention megawatts. These do, and the basis matters: a figure the applicant stated for the project is a different claim from a generator nameplate, which is backup plant rather than sellable load.
| Capacity | Basis | The filing |
|---|---|---|
| 9 MW | Capacity stated in the filing | Spc Qts Sat2 - Dc1 9 MW Fitout |
| 2.25 MW | Capacity stated in the filing | Interior remodel to existing Data Center to replacement of six 2250 KVA UPS System including batteries. |
| 2.25 MW | Capacity stated in the filing | Interior remodel to existing Data Center, to replacement of six 2250 KVA UPS System , including batteries. |
The most recent filings on the record
| Filed | Named on the filing | What it says | Type |
|---|---|---|---|
| 30 June 2026 | Not an identifiable operator | Bexar Data Center | Type not stated |
| 9 April 2026 | CyrusOne | Minor Plans - CyrusOne SAT3 | Type not stated |
| 9 April 2026 | CyrusOne | CyrusOne SAT3: Unit 2 | Type not stated |
| 17 March 2026 | QTS | QTS - 8535 Potranco Rd | Type not stated |
| 9 February 2026 | Microsoft | Microsoft Sat 8990 Data Center Project Site | Power and cooling |
| 9 February 2026 | QTS | QTS - 8535 Potranco Rd | Type not stated |
| 9 February 2026 | Not an identifiable operator | ePlan: Commercial Expedited Review -[BETTER BUILDER] Interior Remodel and Change of Use to Data Center - Sec 2 Floors 3... | Tenant fit-out |
| 21 November 2025 | STACK Infrastructure | Stack Equipment Sa | Power and cooling |
Collected from City of San Antonio open permit data, TCEQ air permit search, City of Austin plan review cases and City of Austin issued construction permits. A permit or air-register entry documents a site or proposed work. It does not establish current construction or available space, and no public filing anywhere discloses what is contractible at a named building. That answer comes from an operator call, which is the part we do by hand. See how we verify capacity.