How much does colocation cost in Dallas-Fort Worth?
Recent quotes we received for Central Time Region / Midwest ran $245 to $295 per kW per month for up to 500 kW, falling to $160 to $190 above 1 MW. CBRE's published asking band for Dallas-Fort Worth is $160 to $185 per kW per month for 250 to 500 kW.
| Deployment | Monthly rate | Source |
|---|---|---|
| Up to 500 kW | $245 to $295/kW-mo | Our quotes |
| Over 500 kW to 1 MW | $200 to $240/kW-mo | Our quotes |
| Over 1 MW | $160 to $190/kW-mo | Our quotes |
| 250 to 500 kW, asking rent | $160 to $185/kW-mo | CBRE, North America Data Center Trends H1 2026, first half of 2026 |
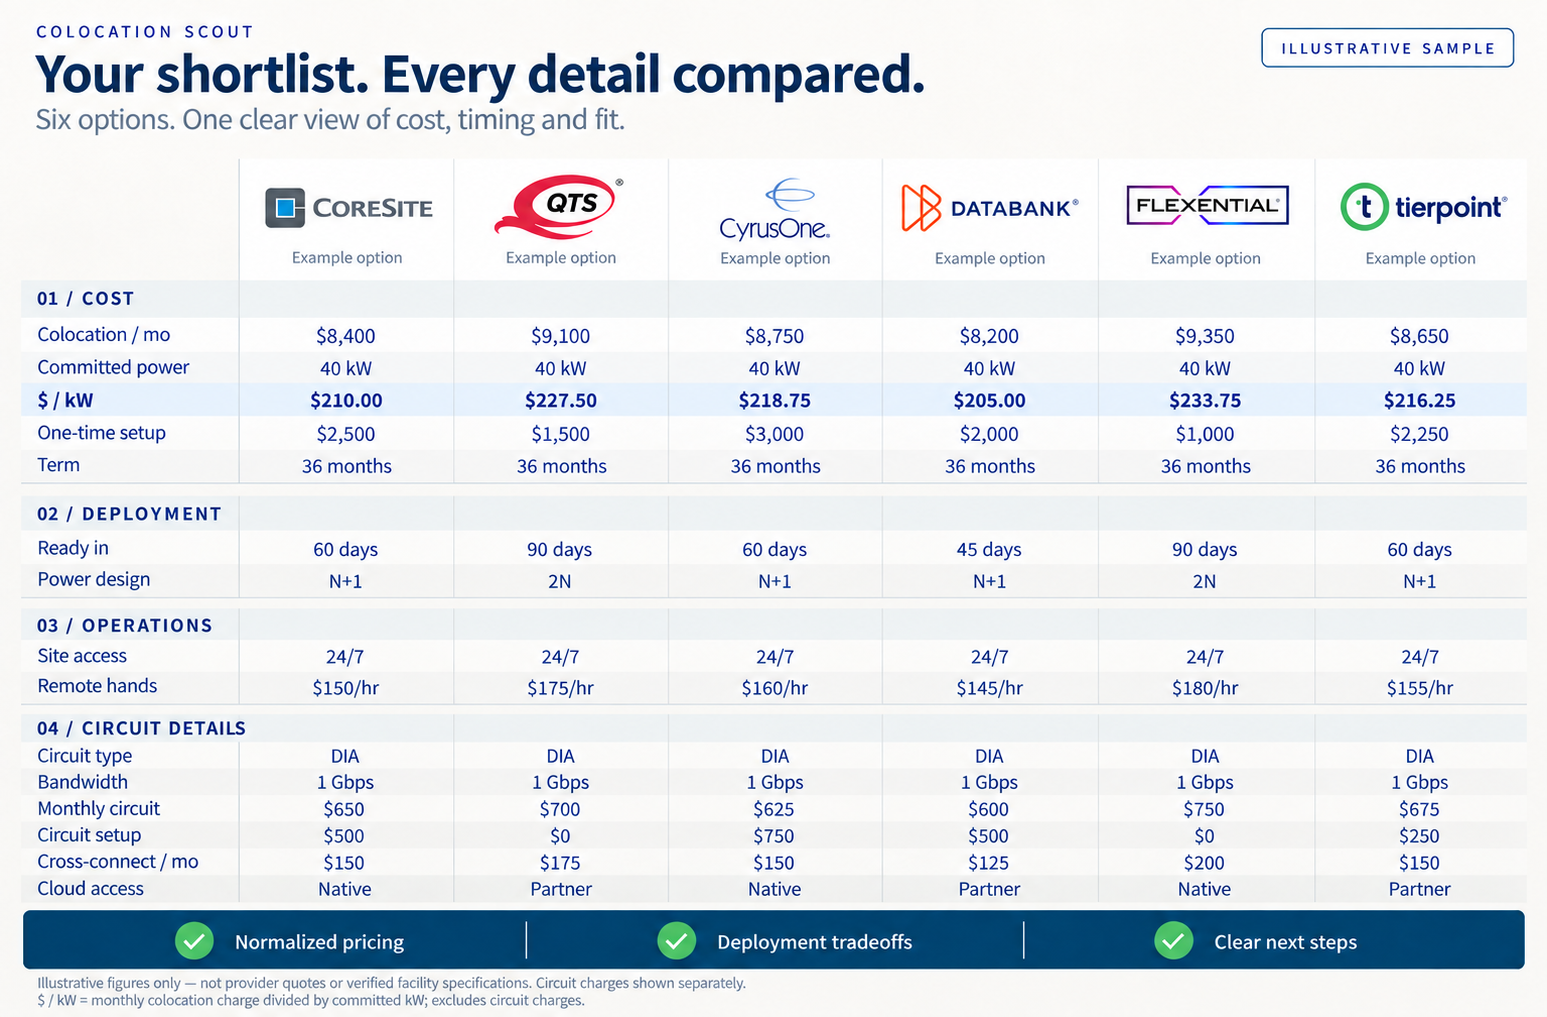
Smaller deployments cost more per kW. These are recent quotes we received, not a statement that space is available. Cross-connects, remote hands and one-time setup are extra. Operators often give 2–3 free months on a new term. See every region's quote ranges.
Dallas cabinet and cage prices
In Dallas-Fort Worth a full cabinet runs $1,000 to $2,100 a month and a four-rack private cage $4,000 to $17,100. Smaller deployments are priced per cabinet or per cage rather than per kW. These are not provider offers, and a building on this page is not a claim that space is available in it.
| Requirement | Monthly range | What it assumes |
|---|---|---|
| 1 to 2U | $100 to $240/mo | Basic power and internet allocation |
| Quarter or half cabinet | $700 to $1,425/mo | Shared cabinet environment |
| Standard full cabinet | $1,000 to $2,100/mo | Typical 3 to 5 kW commit |
| 10 to 20 kW high-density cabinet | $1,700 to $4,500/mo | Cooling method must be validated |
| Private cage | $4,000 to $17,100/mo | Four-rack starting profile; density drives spread |
Taxes, cross-connects, bandwidth and one-time charges are extra. How power is billed is covered in how colocation power is billed.
Flat asking rents make the escalator and the renewal clause the most important terms in the document, because they decide what happens after the market stops being flat. Convert both quotes to cost per usable kW, confirm the power basis, and model the escalator to term end. The pricing benchmarks page carries the published figures to check against.
What the total monthly Dallas cost includes
Cabinet and power
Normalize allocated power, usable IT load, metering and overage language. A cheaper per-kW quote can provide less deployable power.
A/B and cooling
Validate dual-feed assumptions, reserved capacity and the cooling approach at the required rack density.
Bandwidth and operations
Add cross-connects, carrier ports, cloud access, remote hands and any after-hours minimums.
Install and escalators
Include cages, cabinets, cabling, turn-up, deposits, annual increases and any utility or power pass-through.
How long Dallas space takes to deliver
Most DFW construction is preleased before it delivers. The sourcing profiles below are search parameters, not current inventory.
| Option | Footprint | Usable power | Cooling support | Estimated delivery |
|---|---|---|---|---|
| Cabinet search | 1 to 4 cabinets | 5 to 80 kW | Air or containment; liquid by review | Target 30 to 90 days |
| Cage search | 4 to 20 cabinets | 20 to 250 kW | Density-specific engineering review | Target 60 to 150 days |
| Suite search | 250 kW to 1 MW | Contracted usable kW to be defined | Air, RDHx or liquid-ready by facility | Target 4 to 18 months |
Get Dallas colocation prices for your setup
Tell us the racks, power and timing you need. A scout comes back with matching Dallas-Fort Worth options and quoted prices.
Capacity operators are offering here
- 205 kW in Dallas-Fort Worth, available now (confirmed October 22, 2026) AC-003
- 250 kW in Dallas-Fort Worth, available Q1 2027 (confirmed October 22, 2026) AC-001
Operator-reported and dated, not a reservation. The building is named on a call. See every listing.
What providers in Dallas-Fort Worth post as a list price
Most colocation in Dallas-Fort Worth is quoted, not posted. The provider below is the exception: it publishes a monthly price on its own website, and every row links to that page. It is a smaller regional operator. The large operators here do not publish prices at all, so read these as a floor and a sanity check, not as what an enterprise contract lands at.
| Monthly | Provider | Offer | Power included | Per usable kW | Bandwidth |
|---|---|---|---|---|---|
| $649 | Cloudnium | Full cabinet, 42U. DAL-1, Dallas | 20A at 120V (1.92 kW usable) | $338 | 1 Gbps |
| $1,099 | Cloudnium | Full cabinet, 42U, higher power. DAL-1, Dallas | 30A at 208V (4.99 kW usable) | $220 | 1 Gbps |
Each price was read on the provider's own page on the date shown. Usable kW is 80% of the circuit rating, with a redundant A+B pair counted once, and is only worked out where the provider states both amps and volts. "From" is the provider's own word for a starting price. Providers whose networks carry spam or abuse flags are left out whatever their price. A posted price is not availability, and bundles differ in bandwidth and power, so compare the whole row rather than the first column. How power is billed is covered in how colocation power is billed.
Send it over and a scout will tell you how it compares with these posted prices and with the published benchmarks for this market. There is no obligation.
Who is actually plugged in across Dallas-Fort Worth
A building existing and a building being connected are different facts, and only one of them decides whether your traffic can get where it needs to go cheaply. These figures come from PeeringDB, which the network operators themselves maintain, so every row below links to the building's own public entry.
| Measure | Figure | What it means |
|---|---|---|
| Buildings listed | 58 | Registered in PeeringDB across Dallas-Fort Worth, by 28 operators |
| Buildings with a network present | 49 | 9 carry no network presence, which usually means single tenant or simply unregistered |
| Network presences | 949 | Counted per building, so a carrier in three buildings counts three times |
| Internet exchange presences | 78 | Where you can reach many networks through one port instead of many cross-connects |
| Carrier presences | 100 | The physical transport choice you can buy without leaving the building |
| In the densest building | 18% | Equinix DA1 - Dallas holds 168 of the market's network presences |
The most connected buildings here
| Networks | Building | Operator | Exchanges | Carriers |
|---|---|---|---|---|
| 168 | Equinix DA1 - Dallas | Equinix, Inc. | 5 | 8 |
| 104 | Equinix DA3 - Dallas | Equinix, Inc. | 6 | 6 |
| 81 | Equinix DA6 - Dallas | Equinix, Inc. | 6 | 6 |
| 68 | Digital Realty DFW (2323 Bryan St) | Digital Realty | 4 | 3 |
| 61 | Equinix DA - Dallas (previously Infomart Dallas) | Equinix, Inc. | 3 | 4 |
| 54 | Equinix DA11 - Dallas | Equinix, Inc. | 3 | 4 |
| 48 | Equinix DA2 - Dallas | Equinix, Inc. | 5 | 6 |
| 42 | DataBank Dallas (DFW1) | DataBank, Ltd. | 4 | 3 |
From PeeringDB, which is maintained by the network operators present in these buildings rather than by the landlords, which is what makes it worth more than a directory. Two limits. Entries are voluntary, so a building showing no networks may be single tenant or may simply never have registered. And a network being present says nothing about whether the building has space, power or a price for you: that is still a call.
Q1 2026 market profileDallas-Fort Worth by the numbers
Dallas is the fastest-growing large data center market in the country, and the only top-four market where asking rents did not move last year.
| Measure | Figure | Context |
|---|---|---|
| Total inventory | 1,249.4 MW | Third-largest US colocation market, up 43.7% year over year |
| Asking rent change | Unchanged | The only top-four market that did not reprice in Q1 2026 |
| Overall vacancy | 2.4% | The loosest of the top four, though still historically tight |
| Net absorption | 470.8 MW | Up 424.0 MW year over year |
| Under construction | About 700 MW | Roughly 94.5% preleased |
| Industrial power | About $0.0972/kWh | Roughly 23% below the national average |
Sources: CBRE Dallas-Fort Worth market profile and CBRE Global Data Center Trends 2026. Figures describe the metro market, not availability at a particular building.
Rents held while the market absorbed 470.8 MW. That is a market keeping pace, not a soft one. If the pipeline tightens, flat ends, which argues for a longer term now.
The submarkets, and what each is good for
A core interconnection site and a western campus are different products at different prices. Decide which you are buying before comparing quotes.
Dallas core and the Infomart corridor
The historic carrier and interconnection center. The answer for peering, cloud on-ramps and latency-sensitive workloads rather than for cheap megawatts.
Richardson and Plano
North corridor enterprise colocation with established multi-tenant facilities and solid carrier choice. Well suited to cabinet and cage requirements.
Fort Worth and west
Where land and power support campus-scale development. Larger contiguous blocks and longer timelines, and the corridor most exposed to transmission upgrade timing.
Outer Metroplex
Where much of the planned greenfield capacity is staged. Availability the core cannot match, at the cost of drive time and carrier depth.
Power is cheap here. Getting it connected is the risk.
Dallas power runs about 23% below the national average, which is why large requirements land here. The constraint is moving it. New capacity depends on the Oncor Regional Transmission Plan, and the power queue now restricts speculative positions.
On 3 August 2026 Texas halted approvals for any data center seeking a new ERCOT grid connection, pending a state audit with no end date. Energized capacity and connected buildings under construction are untouched. The roughly 3 GW of planned greenfield beyond today's pipeline is not.
Is this capacity energized, under construction with a connection, or waiting on an ERCOT approval that has not been granted? The three are often quoted at similar rates and carry very different risk. Sites with their own on-site generation sit outside the freeze. Central Texas is under the same rule, covered on the Austin and San Antonio guide.
Reported by the Texas Tribune on 3 August 2026 and KERA News on 4 August 2026.
When Dallas is the right call
- Power cost. About 23% below the national average.
- Rate stability. The only top-four market with unchanged asking rents.
- Room to negotiate. 2.4% vacancy is tight, but the loosest of the four largest markets.
- Central reach. Workable latency to both coasts and strong regional network density.
- Equipment tax. Texas exempts qualifying data center equipment from sales and use tax. Confirm with a tax advisor and model the case without it.
Dallas does not have Ashburn's interconnection depth. If the widest carrier and cloud on-ramp choice is the priority, compare Northern Virginia. For an interior second site, price Oklahoma too, and check the pricing benchmarks page before paying a premium elsewhere.
What has been announced in Dallas-Fort Worth
Announcements are not filings. Nobody has to build what they announce, the figure is the one the developer chose to publish, and the date moves. They are here because megawatts are what a requirement is measured in, and because the size of what is coming changes who will take your call. Every figure below links to a published report that states it, and was checked against at least one other independent report before it was written down.
| Capacity | Operator | Project | What was announced |
|---|---|---|---|
| 1.8 GW | PowerHouse Data Centers and Provident | DFW campus | 768 acres, 24 buildings over three phases. Announced switchyard capacity |
| 550 MW | Yondr | Lancaster campus | 163 acres south of Dallas |
| 311 MW | Big Digital Energy | Campus outside DFW | Land acquired |
| 220 MW | STACK Infrastructure | Dallas campus | Six buildings at 36 MW each, on-site Oncor substation |
| 48 MW | Stream Data Centers | Wilmer II | First building of a campus planned to reach 240 MW |
Announced capacity is collected by hand from trade reporting and company statements, and each figure links to the report it came from. It is kept apart from the permit record below and never added to it: one is a document a jurisdiction issued, the other is a plan a company published. Neither is availability.
Every Dallas-Fort Worth facility we track
288 data centers across Dallas-Fort Worth, from our verified inventory. It is the layer that says whether a building exists yet, which no permit record answers directly.
| Status | Facilities | What it means for a search |
|---|---|---|
| Operational | 99 | Standing and running. The only layer that can hold a requirement this year |
| Under construction | 28 | Steel is up. Reachable for a date 6 to 18 months out, and usually pre-leasing now |
| Planned | 161 | Announced or entitled, not yet built. Treat every date on these as a forecast |
| Building area on file | 71,130,037 SF | Across the 179 facilities where a size is recorded, of 288 |
| Largest single building | 8,580,000 SF | STACK Infrastructure, Fort Worth |
Operators with the most facilities here: CyrusOne (28), QTS (28), Digital Realty (23), Stream Data Centers (18), DataBank (16), Compass Datacenters (14), STACK Infrastructure (14), NTT Global Data Centers (11), Skybox Datacenters (11), DartPoints (8).
Where they cluster: Dallas (41), Lancaster (41), Plano (26), Red Oak (25), Richardson (20), Fort Worth (19).
The largest buildings coming to this market
189 facilities here are under construction or planned. These are the ten largest by floor area, and a size on file is not a promise of a delivery date.
| Operator | Status | Building size | Where |
|---|---|---|---|
| STACK Infrastructure | Planned | 8,580,000 SF | Fort Worth, TX |
| DartPoints | Planned | 1,350,000 SF | Dallas, TX |
| DartPoints | Planned | 1,100,000 SF | Dallas, TX |
| Digital Realty | Planned | 832,000 SF | Midlothian, TX |
| Digital Realty | Planned | 810,000 SF | Midlothian, TX |
| Digital Realty | Planned | 810,000 SF | Midlothian, TX |
| Digital Realty | Planned | 810,000 SF | Midlothian, TX |
| EdgeConneX | Planned | 700,500 SF | Lancaster, TX |
| EdgeConneX | Planned | 700,500 SF | Lancaster, TX |
| EdgeConneX | Planned | 700,500 SF | Lancaster, TX |
From our verified inventory rather than from a public record, so these rows carry no filing link and street addresses are held back. These buildings are verified, which is not the same as their space being available: every facility above may be full, pre-leased, or closed to your size. Finding out is a call, not a lookup. See what a verified building does and does not mean.
What the public construction record shows in Dallas-Fort Worth
Building permits from five DFW jurisdictions (Dallas, Fort Worth, Denton, Collin, Irving) plus TCEQ air permits. South DFW / Irving planning satellites and Dallas CAD Irving/Garland appraisal inventory stay on their own keys; the DFW quarterly report lists CAD as inventory, not permit counts. Every figure below is a count of filings we collected ourselves, and every row links to the record it came from.
| Measure | Figure | What it means |
|---|---|---|
| Filings we track | 231 | Deduplicated. Across 6 sources, July 1980 to October 2026 |
| Filed in the last 12 months | 36 | The live rate of construction activity, which is the number that moves |
| Tenant fit-out filings | 43 | A customer is landing in a named building. The strongest signal in the set |
| New building filings | 28 | Shell and site work, which is capacity two years out, not now |
| Distinct addresses | 125 | Separate sites in the record, not separate buildings |
| Largest capacity in the record | 196 MW | Stated on 2 of 231 filings. Capacity is rarely published, so this is a floor, not a market total |
| Largest floor area filed | 504,219 SF | One permit, not a campus total. Floor area is published far more often than capacity |
| Operators we can name | 15 | 97 of 231 filings name a recognizable operator. The rest name an engineer, a builder or a holding company |
| Filings with no date published | 14 | The source publishes the facility, not the filing date |
Operators appearing by name: QTS (36), Aligned (23), CyrusOne (9), STACK Infrastructure (7), DataBank (3), Flexential (3), T5 Data Centers (3), Core Scientific (2).
The filings that state a capacity
Most permits never mention megawatts. These do, and the basis matters: a figure the applicant stated for the project is a different claim from a generator nameplate, which is backup plant rather than sellable load.
| Capacity | Basis | The filing |
|---|---|---|
| 196 MW | Capacity stated in the filing | Edged Energy Outpost Building 2 |
| 196 MW | Capacity stated in the filing | Edged Energy Outpost Building 2 |
The most recent filings on the record
| Filed | Named on the filing | What it says | Type |
|---|---|---|---|
| 6 October 2026 | Edged Energy | Edged Energy Nfl | Power and cooling |
| 25 September 2026 | Not an identifiable operator | DFW SPE 2 LLC | Type not stated |
| 24 September 2026 | Not an identifiable operator | Coresite Data Center | Type not stated |
| 16 September 2026 | Not an identifiable operator | Data Center Enclosure & MEP Upgrades/Tarrant County College District | Tenant fit-out |
| 10 September 2026 | Not an identifiable operator | Cemco-403 & 365 Cbp Clocktower Data Center | Power and cooling |
| 3 August 2026 | Not an identifiable operator | ACS Data Center Phase I Substation | Power and cooling |
| 3 August 2026 | Not an identifiable operator | Edged Energy Outpost Building 2 | Type not stated |
| 3 August 2026 | Not an identifiable operator | Edged Energy Outpost Building 2 | Type not stated |
Collected from TCEQ air permit search, City of Fort Worth permit records, City of Irving development permits and commercial permits, City of Dallas permit records, Plano, Allen and McKinney permit records and City of Denton permit records. A permit or air-register entry documents a site or proposed work. It does not establish current construction or available space, and no public filing anywhere discloses what is contractible at a named building. That answer comes from an operator call, which is the part we do by hand. See how we verify capacity.